The Premium Market, in Numbers: Bengaluru’s 2026 Mid-Year Read
Market Trends · 03 July 2026
Bengaluru enters the second half of 2026 with the country’s fastest price growth, record launch volumes, and a market that has decisively gone premium. The numbers, decoded.
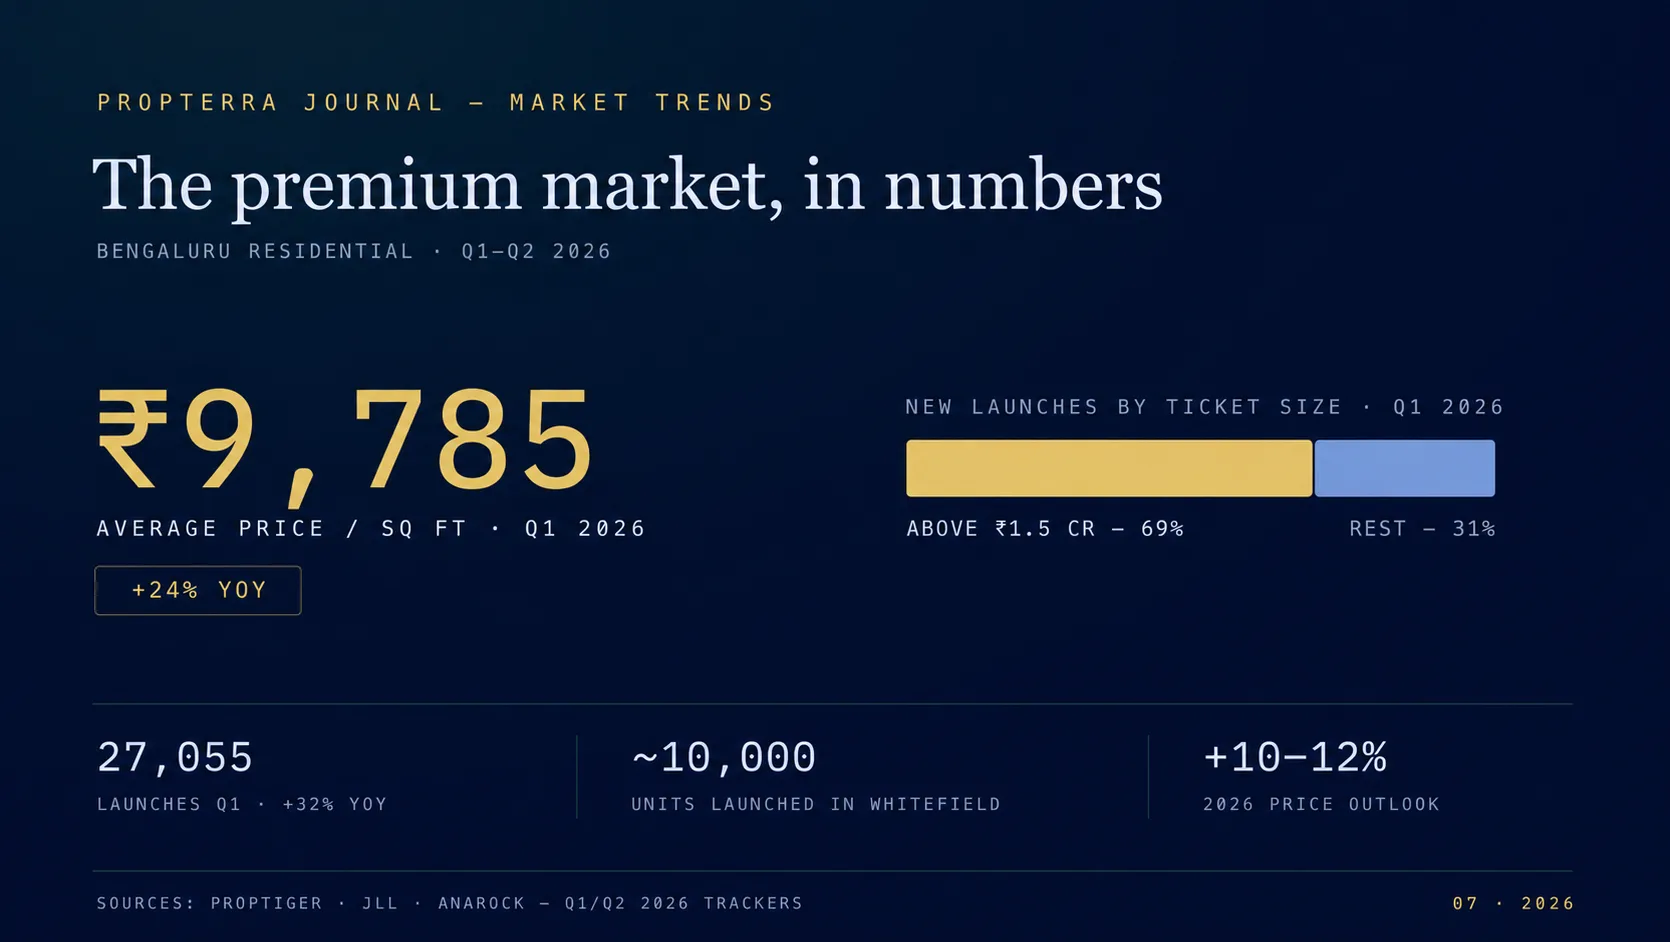
Halfway through 2026, Bengaluru is the standout residential market in the country. Average housing prices touched ₹9,785 per sq ft in Q1, up 24% year-on-year per PropTiger’s tracker, the sharpest appreciation among the top cities and second in absolute terms only to Mumbai’s metropolitan region. Underneath that headline, the composition of what is being built has changed in ways every buyer should understand.
A market that has gone premium
Of the 27,055 units launched in Bengaluru in Q1 2026, itself a 32% jump year-on-year, roughly 69% were priced above ₹1.5 crore. The pattern held into Q2, with high-end and luxury supply taking a 58% share of new launches. Developers are consciously building larger, better-specified homes for upper-mid and affluent buyers, and nowhere is that clearer than Whitefield, which alone absorbed nearly 10,000 new launches in the first quarter.
The east side story
The corridors we track have led this cycle rather than followed it. Whitefield now trades in a broad ₹7,500–11,000 per sq ft band and Sarjapur Road at ₹7,200–10,500, and Sarjapur Road’s run is the defining story of this cycle: from about ₹6,050 per sq ft in late 2021 to roughly ₹10,800 by mid-2025, a 79% climb in under four years, powered by ORR job density, school infrastructure, and the metro plans we covered in our Blue Line note.
Watch the inventory
The number that deserves your attention is unsold inventory: up 34% year-on-year to around 79,180 units, while quarterly sales grew only about 1%. That is not a crash signal, absorption remains healthy by historic standards, but it does mean the market is becoming selective. Well-located projects from credible developers keep pricing power; commodity supply in over-served pockets will have to negotiate. For buyers, that gap is opportunity.
What we’re telling clients
Industry forecasts put Bengaluru’s 2026 price growth at 10–12%, led by exactly the premium segment this market now manufactures. Our read: premium under-construction homes in corridor locations with confirmed infrastructure catalysts remain the sweet spot, but the underwriting bar is higher than it was in 2023. Developer track record, K-RERA status, realistic possession dates, and carpet-area economics decide outcomes from here, not the market tide. That diligence is precisely the work we do before a project reaches your shortlist.